
Brazil
Export volume fluctuates within new parameters
Beef export volumes have declined significantly since late July, partly due to weaker demand after China’s 2026 quota was filled and partly because of lower production.
Oct 14, 2026
See moreWith your subscription you will have access to more than 12,000 articles and 29 indicators, with information on the Mercosur beef and sheep export market to the rest of the world.
Ideal formula of people to obtain excellent and reliable information.
We provide accurate and reliable information to make strategic decisions in the livestock and meat market.
CLIENTS
REPORTS
DATA
UNIQUE USERS
Subscribe to our weekly newsletter and receive the latest market insights, price trends, and industry analysis directly in your inbox.
 Full Access
Leading Weekly Publication in Beef and Sheep Export from Mercosur to the World. Prices, Trends, and Key Analysis for the Livestock and Meat Market
Last update 10/12/2026
Latest
Beef export volumes have declined significantly since late July, partly due to weaker demand after China’s 2026 quota was filled and partly because of lower production.
The revised Mercosur steer price index exceeded US$ 5.00/kg carcass weight for the first time on record, driven mainly by the rapidly strengthening Brazilian market, where the consolidation of the herd rebuilding phase is reducing finished cattle supplies. Prices also increased in the other three countries in the region.
A Uruguayan exporter reported Russian enquiries to WBR at US$ 2,000/t FOB for liver, US$ 4,650/t FOB for tongue and US$ 2,100/t FOB for heart. These were bids received, with no confirmed transactions.
A regional operator reported sales of Uruguayan beef to Brazil concluded last week.
Chile’s beef market remains quiet, with Brazilian 19-20 cut sets trading at around US$ 7,400-7,500/t. A Paraguayan exporter confirmed retail-segment sales to WBR at US$ 8,500/t. The transaction provides a price indication above the levels reported by other operators for Paraguayan beef.
The US beef market showed signs of stabilizing over the past week following the price adjustments recorded since September.
Argentine market sources reported prices of US$ 6,200/t CFR for in-quota 90 VL, but virtually no business due to intense competition with Brazil in this segment. A trader currently in Florida described commercial activity in the state as subdued. “Activity is very weak. Tourism is down, consumption is down, fuel and interest rates are very high—no change,” he told WBR.
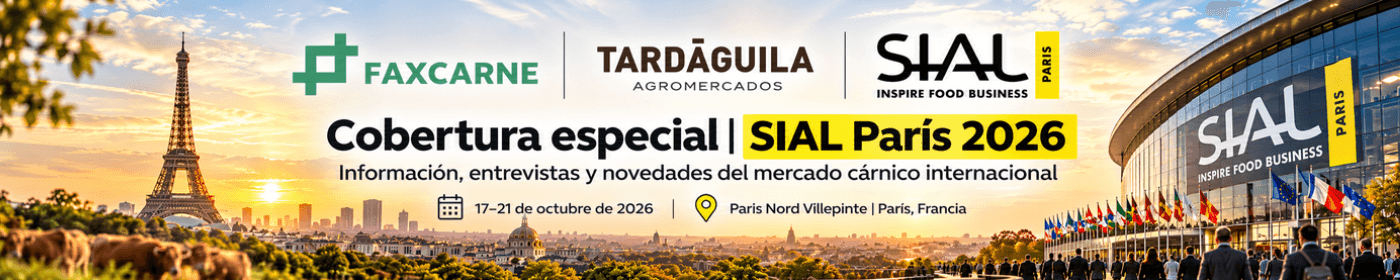
A large share of Mercosur exporters remains cautious ahead of the SIAL trade show in Paris, which begins next Saturday and runs through Wednesday. Face-to-face negotiations could provide new price indications for a market facing downward pressure on chilled beef.
The lack of commercial agreements is creating uncertainty over the start of the next production cycle for Israel. Some teams may travel without prices having been agreed, while Paraguayan exporters warn that another increase in cattle prices would squeeze processing margins.
China’s beef market is beginning to regain momentum following the holiday break, although orders remain within normal levels for now. A regional operator reported new transactions for several cuts, with no signs of a significant acceleration in demand.
Between January and September 2026, 21.0 million cattle were slaughtered at federally inspected plants (SIF), down 7.5% from a year earlier. SIF plants are authorized to export.
Finished cattle prices accelerated their upward trend over the past week. This was the sixth consecutive week of recovery in Brazilian real terms, with prices gaining a cumulative 6.9% and reaching record nominal levels.
INAC reported that 9,907 sheep were slaughtered in the week ended October 10, compared with just 1,152 head the previous week. This was still 42% below the 17,093 head processed in the same week of 2025. Lambs totaled 6,907 head, accounting for 70% of total slaughter.
